
Not financial advice. This site shares one person's personal experience with spending and investing — it is not a recommendation for you. All investing carries risk. Full disclaimer

Thoughts, Mistakes & Lessons

Real talk about what I do.

No hype. No hot tips. Just honest reflections on what I do with my own money — the ETFs I hold, the mistakes I've made, and what I've learned along the way. Not advice. Just one person's journey.

For educational purposes only. This content provides general information about spending habits, saving and personal finance. It is not financial advice or a recommendation to take any financial action. Always consider your own circumstances before making financial decisions.

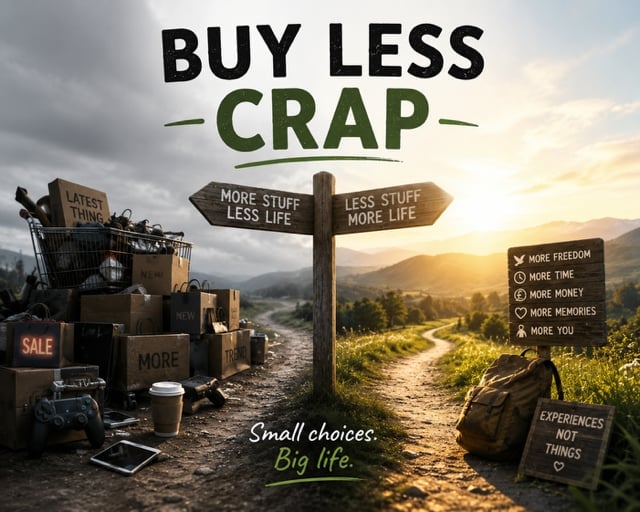
Buy Less Crap poster with directional signs on a forest path contrasting a pile of consumer goods on the left (latest things, sale, more stuff, more life) with a backpack and the path of experiences on the right (more freedom, more time, more money, more memories, more you)
Small choices. Big life. The whole website in one picture.

The reality of impulse spending

Funny because it's true.

Two posters that capture the difference between buying what you need and buying what you don't. A bit of humour goes a long way when the topic is money.

Couple on the sofa with a dog surrounded by cardboard boxes, satirical financial goals poster — my wallet and I had a meeting, we're trialling a bold new strategy of buying things we actually need, save more, buy less crap, think before you buy, impulse buy prevention
My wallet and I had a meeting. We agreed on a bold new strategy.
Man in pyjamas on the sofa surrounded by cardboard boxes from impulse shopping, holding phone with Free Delivery sold message, satirical poster — I work hard so my cart can have cool stuff, said no bank balance ever
I work hard so my cart can have cool stuff. Said no bank balance ever.
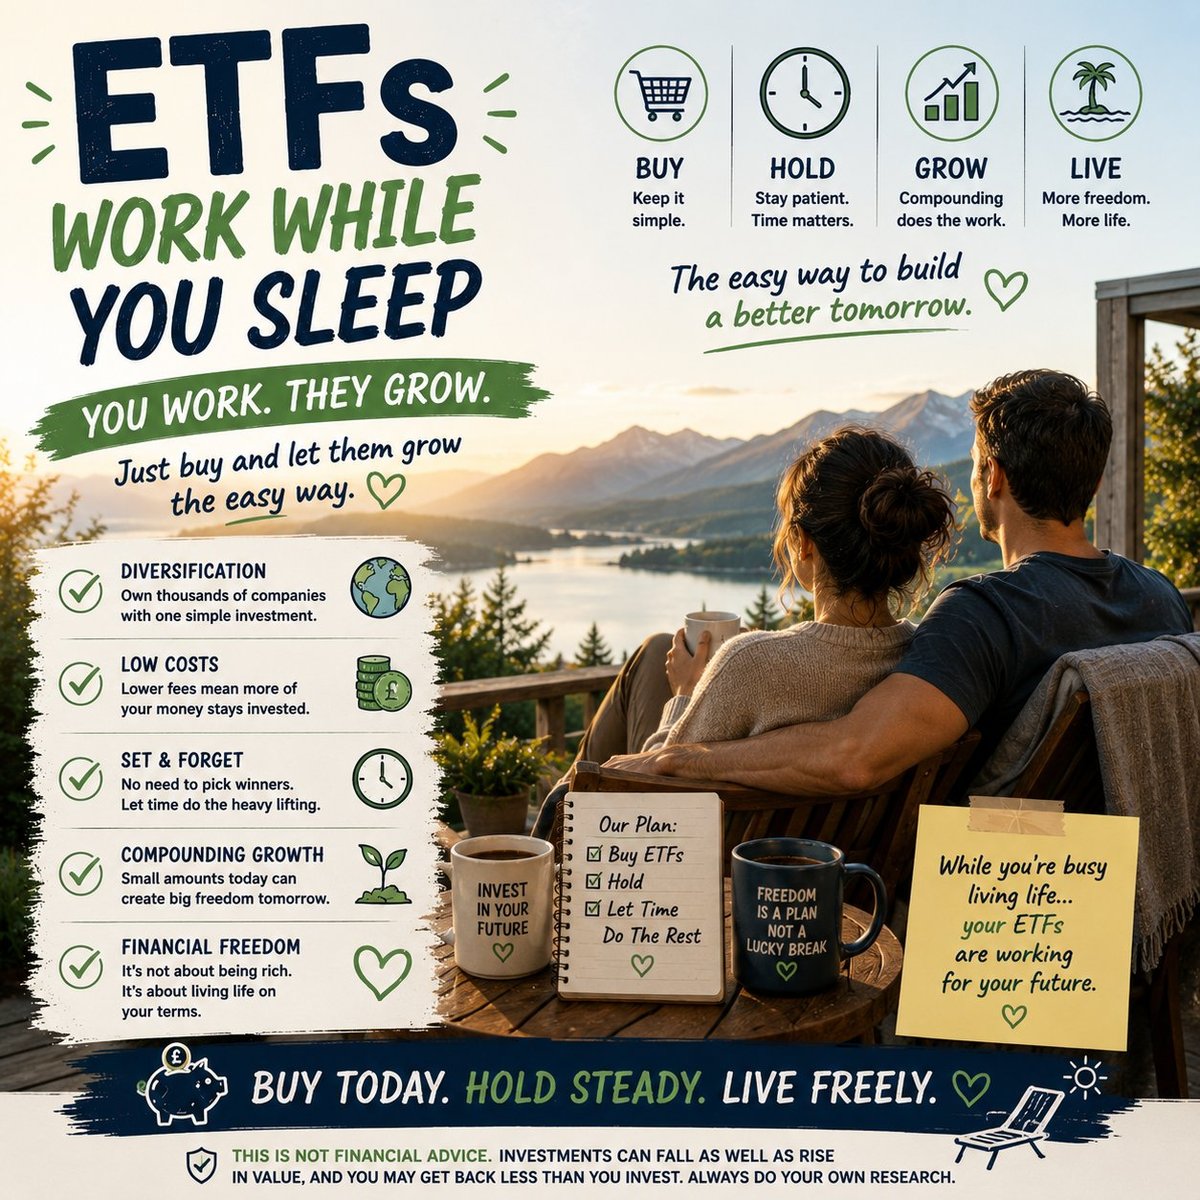
Infographic about ETFs explaining how they work passively with benefits like diversification, low costs, and compounding growth illustrated with a couple watching mountains by a lake
ETFs: diversification, low costs, compounding growth. The sooner you start, the better.

Sorted newest first · 79 articles and counting

10 min read
Getting StartedFirst Year InvestingIndex FundsInvesting HabitsBeginners

Your First Year of Investing: What To Actually Do (UK Guide)

Everything online is about the exciting part of investing — the fund that doubled, the share that took off. Almost nothing is about the first year, because the first year has no story in it. That's the point. A plain-English UK guide to the four decisions that actually matter in year one, what to do when the value falls (do nothing, keep contributing), and the mistakes that cost beginners the most. The first year isn't about picking winners — it's about becoming a person who invests.

Read more
7 min read
The Wingle UniverseW. IngleBooksHumourFunWork

I'm The Manager. Don't Ask Why. — The Book I Forgot I Wrote

I recently wrote a very confident article on this website listing every book in the Wingle Universe and telling everyone I knew how many there were. I did not. I'm The Manager. Don't Ask Why. had been sitting there the whole time. This is the one about middle management, sticky notes, meetings about meetings, and a donkey who is somehow still the most competent person in the building. Available now on Amazon.

Read more
8 min read
Buy Less CrapThe Wingle UniverseW. IngleBooksHumourFunCommon Sense

I Accidentally Wrote Five Books. Don't Ask Why.

I built a website about buying less crap and investing the difference — and then, somehow, I wrote five books about a King, a Donkey and a goat called Keith. I'm The King. Don't Ask Why. went first, then I'm Still The King, I'm The King Now, The Wingle Chronicles Book 4, and now I'm The King. Probably. Don't Ask Why. — the fifth, officially stamped 5.62.5, which is not a number that means anything. Here's the honest, funny, slightly baffled story of how a bloke writing about index funds ended up running a fictional universe, what's in each book, and where to buy them. Spoiler: I still don't know why. Nobody does. That's the joke, and it's also the point.

Read more
9 min read
RetirementInvestingISAMoney MindsetCommon Sense

How to Start Investing in the UK Over 50 — Boring, Slow & Late (The Complete Guide)

Starting investing in your 50s or 60s in the UK? This is the guide I wish someone had handed me. The honest maths of a late start (you may still have a 10 to 30 year horizon), the order of operations that actually matters — clear expensive debt, capture the full employer pension match, build 3–6 months of emergency cash, fill the Stocks & Shares ISA allowance, then a SIPP if it suits you — plus the three UK accounts worth thinking about, why diversification matters MORE when you're older rather than less, the six mistakes that turn a late start into a bad ending, and a seven-question FAQ. Written by a 66-year-old UK investor who has been where you are. Not financial advice.

Read more
9 min read
Spending HabitsLifestyle CreepMoney MindsetCommon SenseInvesting

The Six Most Expensive Ways to Look Rich (And Why I Own None of Them)

A funny, honest look at the six priciest status symbols people use to look wealthy — the flashy German car on finance, the expensive watch, the boat, the limited-edition sneakers, the private school you can't quite afford, and the holiday where you don't check prices — and why each one quietly makes you poorer. Includes the 'hedge fund manager rule' (you look rich when you stop trying to), a 5-question test to stump any 'look at me' purchase before it empties your ISA, and what actually makes you feel wealthy once the audience goes home. In-voice, plain-English and gently self-deprecating from a 66-year-old UK investor who owns none of them. Not financial advice.

Read more
8 min read
Spending HabitsCommon SenseMoney Mindset

The 'Buy Less Crap' Checklist: 5 Questions to Ask Before You Buy Anything (Save Money, UK)

Before you buy anything non-essential, run it past this 5-question Crap Test — need or want, will I use it in a year, am I fixing a feeling, is there a cheaper alternative, and what could the money grow into if invested. Plus the bonus 24-hour 'sleep on it' rule. A plain-English, in-voice guide to stopping impulse buys, buying less, and investing the difference — from a 66-year-old UK investor who spent decades unlearning the impulse buy. Built from the site's own Crap Test, 24-Hour Rule and Before You Buy Anything pages.

Read more
9 min read
RetirementFinancial IndependenceInvestingCompoundingMoney MindsetUK Personal FinanceCommon Sense

The 4% Rule Explained: How Much Money Do You Actually Need to Retire? (UK)

How much money do you actually need to retire? The 4% rule — take your annual spending, multiply by 25, withdraw 4% a year — is the famous clue, and this plain-English UK guide explains it properly rather than parroting it. Where it came from (the 1998 Trinity Study), the exact step-by-step calculation, what it quietly assumes (US data, a fixed withdrawal, spending the pot to zero), and why a flexible approach beats a rigid one every time. Plus the UK specifics that change the maths in your favour: State Pension and defined benefits forming a guaranteed base, and ISAs and SIPPs providing the flexible growth on top. Whether you're 35 or 65, this turns the terrifying 'how much do I need?' into a boring, countable number you can actually aim at. From a 66-year-old UK investor who's running these sums for himself. Not financial advice.

Read more
10 min read
Getting StartedUK Personal FinanceISAInvestingTaxETFsCommon SenseCompounding

What Is a Stocks & Shares ISA? The Complete Beginner's Guide for UK Investors

A Stocks and Shares ISA is the single most useful wrapper a UK investor can own — but most beginners never open one because the name sounds harder than the thing actually is. This plain-English guide covers everything: what it actually is (a tax-free account for investments, not just savings), how the £20,000 use-it-or-lose-it annual allowance works, why growth and dividends inside it are free of UK income tax and capital gains tax for as long as the money stays in, what you can hold (ETFs, index funds, shares — you don't need to pick stocks, one broad fund like VWRP or VUAG is plenty), and how it differs from a Cash ISA, a Lifetime ISA and a SIPP. Plus the four beginner mistakes, the exact 15-minute steps to open one with Trading 212, InvestEngine or Vanguard, and whether you should pick an accumulating or income fund. No jargon, from a 66-year-old UK investor who's used ISAs for decades. Not financial advice.

Read more
9 min read
Common SenseSpending HabitsMoney MindsetSustainabilityUK Personal FinanceMinimalism

The Hidden Cost of 'Buying Crap': What Overconsumption Is Actually Doing to the Planet (And Your Wallet)

Buying less crap isn't just a personal-finance strategy — it's an environmental one too. This plain-English guide looks at what overconsumption actually does once it leaves the shopping basket: UK landfill piling up with barely-worn clothes and once-used gadgets, fast fashion's water and carbon footprint, microplastics washing into the ocean, and the manufactured urgency that gets us clicking 'buy' on things we never needed. The genuinely good news: the exact same habit that grows your ISA — pausing, choosing less and better, investing the difference — also shrinks your footprint. No guilt trip, no lifestyle overhaul, just an honest look at the hidden bill behind the price tag, from a 66-year-old UK investor who buys less crap for both reasons.

Read more
9 min read
ETFsVanguardVALLVSMLVXUSGetting StartedUK Personal FinanceCommon SenseInvestingCompounding

Vanguard's New Global ETFs: VALL, VSML & VXUS Explained in Plain English

Vanguard has just launched three brand-new global equity ETFs — VALL, VSML and VXUS — and they're a genuinely big deal for UK investors. This plain-English guide explains what each one actually tracks: VALL, the FTSE Global All-Cap UCITS ETF at just 0.07%, which covers roughly 10,000 companies across the whole world in a single fund and undercuts the beloved VWRP on both cost and breadth; VSML, the global small-cap ETF that catches the thousands of tiny companies the big index funds gloss over; and VXUS, the whole planet's stock market minus America, which balances out an America-heavy portfolio. Plus: how they compare to VWRP and VUAG, whether you should switch (honest answer: usually just direct new money in, don't trigger a taxable sale), and the case for VALL as a true one-fund portfolio. From a 66-year-old UK investor who's already started buying all three — no jargon, not financial advice.

Read more
8 min read
InvestingGetting StartedCompoundingBehavioural FinanceUK Personal FinanceCommon Sense

Pound-Cost Averaging vs Lump Sum: Which Is Actually Better for a UK Investor? (Plain English)

You've got a lump sum — a bonus, an inheritance, a cash ISA that needs to work harder. Do you invest it all today or drip it in over months? On the numbers, lump-sum investing beats pound-cost averaging roughly two-thirds of the time — the money is simply in the market longer. But the honest answer for real humans is richer than the data: DCA isn't stupid, it just costs you a bit of expected return in exchange for sleeping at night. This plain-English UK guide covers what Vanguard's famous study actually found, the one situation where averaging is clearly the right call (your monthly direct debit), and the brutal truth that doing nothing and leaving a lump in cash is the single worst option of all. No jargon, no hype — from a 66-year-old UK investor who'd rather be boring than wrong.

Read more
8 min read
Getting StartedInvestingCompoundingMoney MindsetUK Personal FinanceMotivation

Won't You Thank Yourself for Starting Early? Don't Leave It Too Late

Imagine meeting your future self in 20 years. Will they hug you for starting early, thank you for starting at all — or quietly curse you for putting it off? That imaginary handshake is the most honest judge of the decisions you're making today. This funny-but-inspiring guide to not leaving it too late covers why 'it's too late anyway' is a trap your future self will resent, the brutal-but-fair conversation past-you keeps avoiding, why starting small and starting now beats starting big and starting never, the 'you're going to be 70 anyway' logic that finally got a 66-year-old moving, and how every month you don't start is a month your older you can't get back. The power of starting early isn't magic — it's compound interest and a grateful older you. From a 66-year-old UK investor who knows exactly what 'I should have started sooner' feels like, and who's here to make sure you don't say it to yourself.

Read more
9 min read
Saving MoneyMoney MindsetBehavioural FinanceUK Personal FinanceHabits

The Money-Saving Habit Stack: How to Save More Without Willpower or Deprivation

Willpower is a finite resource that runs out by 8pm on a Tuesday, and 'just try harder to save' is the least helpful advice in personal finance. The people who save well aren't more disciplined than you — they've designed their lives so they don't have to be. This is the system that replaces discipline with design: habit stacking (after my morning coffee, I check my balance), environmental design (delete the shopping apps, remove saved card details, make spending inconvenient), and automation-first (a direct debit that moves money to your ISA on payday, before you can spend it). Past you makes the decision so tired, 8pm-on-a-Tuesday future you doesn't have to. Plus the structural changes that actually move the needle (your rent, your car, your energy tariff — not the coffee), commitment devices that make it hard to quit (fixed-rate savings, telling someone your goal), and the 24-hour rule that's saved me more than any budget. A warm, evidence-based, practical guide to saving more with less effort, from a 66-year-old UK investor who stopped trying to be a financial hero and became a financial architect.

Read more
9 min read
Getting StartedInvestingUK SpecificMoney MindsetCompounding

You Don't Need to Own a Home to Build Wealth: Investing While Renting in the UK, Done Sensibly

Owning a house is not the only road to wealth, and for a lot of renters it isn't even the most sensible one right now. If you rent and feel 'behind' because you don't have a mortgage, you're not — and this post is the proof. The 'get on the ladder' story is more life choice than wealth verdict: buying carries stamp duty, surveys, maintenance and an illiquid, geographically-locked asset, while renting gives you a flexible base and absolutely no boiler emergencies. The real trap was never renting — it's renting AND investing nothing because you've swallowed the message that 'investing is for people with a house.' If you rent, your real wealth decision is invest or don't, not buy or don't. The maths of renting and investing the difference in a simple global index fund inside an ISA or SIPP can genuinely build more wealth than a leveraged single asset. Emergency fund, ISA, SIPP, a small automatic direct debit from your rented kitchen table — that's how a renter builds real, liquid, compound wealth without a single set of keys. A liberating, straightforward guide from a 66-year-old UK investor who's seen both sides of the fence.

Read more
8 min read
Getting StartedMoney MindsetISASIPPCompoundingUK Specific

I Just Got a Windfall — Inheritance, Bonus or a Big Lump. Now What? A Safe, Sensible Order of Operations

The most dangerous time with money isn't when you're broke — it's the six months after a sudden windfall. A bonus, an inheritance, a redundancy payout: easy money gets spent faster than money ever earned it, and the biggest threat is yourself. But a windfall isn't 'spend it on a car' money — it's 'decide deliberately' money. This is the calm, boring, sensible order of operations: park the whole sum somewhere easy-access and do nothing for a month (the temptation is far weaker in week four than week one), then clear high-interest debt first — paying a 20% card off is a guaranteed tax-free 20% return no investment can match — then top up your three-to-six-month emergency fund, and only then invest the rest simply, in broad low-cost index funds inside ISAs and SIPPs for long-term compounding. Treat yourself from one small pre-agreed slice, never the whole. A windfall amplifies your habits, so hand yourself better ones. The calmest guide to suddenly having big money, from a 66-year-old UK investor.

Read more
9 min read
Getting StartedCompoundingMoney MindsetInvestingMotivation

Something Is Better Than Nothing: Why the Smallest Start Beats the Perfect Plan That Never Begins

The most underrated idea in personal finance isn't compounding — it's that something is better than nothing. For years I didn't invest because I only wanted to invest properly: I had a figure in my head, a 'real' amount worth bothering with, and I never quite reached it, so I never quite started. That waiting — the perfect plan that never begins — cost me more than any single perfect plan could have made back. This post is the case for the smallest possible start: why a £20-a-month direct debit you keep doing beats a perfect £1,000 plan you abandon in week two, the zero-day trap and the perfectionism that quietly destroys more wealth than any bad purchase, the crushing maths of why a little beats nothing by an infinite margin, the progress-over-perfection framework, and how to actually become a 'something person' by lowering the bar to the floor, automating, and giving time its head. Compounding is indifferent to the size of the number you hand it — but utterly helpless if you hand it nothing. From a 66-year-old UK investor who waited too long and wishes you didn't. Not advice, just the honest case for starting somewhere today.

Read more
8 min read
InvestingSavingGetting StartedCompounding

The £25-a-Week Habit: How Small, Automatic, Boring Investments Quietly Beat the Big One-Off Wins

Everyone wants the big hit — the lucky stock, the windfall, the moment you can finally 'invest properly.' I waited years for that moment while saving nothing, because £100 a month felt too small to matter. I was completely wrong. The £25-a-week habit — a small, automatic, deeply boring direct debit into a global index fund that you never touch — has quietly built me more real wealth than any one-off decision I ever made. This is the honest maths of what £25 a week grows into over 5, 10 and 25 years, why automatic investing and pound-cost averaging beat willpower and hot stock picks every single time, the £500 one-off vs the £25 habit showdown, how to set up an automatic ISA or SIPP in ten minutes, and the embarrassing mistake of waiting to invest 'properly' that I hope you don't repeat. Small and regular beats big and occasional — boring is the friend of wealth. Not advice — just what a 66-year-old UK investor has learned about the quiet power of showing up weekly.

Read more
9 min read
Money MindsetRelationshipsCommon SenseSpending Habits

Money, Marriage and Friends: How to Talk About Money in Relationships Without It Ruining Them

Money is the thing couples fight about more than anything else — and the thing we're least equipped to discuss. We'll spill our deepest fears over dinner then choke on the simple sentence 'how should we handle our money together?' It's not that money is the real problem in most relationships; it's that money is the lens through which every other problem becomes visible. This guide covers the one conversation nobody has (the money scripts your childhood installed), joint vs separate accounts and the hybrid that actually works, the proportional split that's genuinely fair when incomes differ, lending money to friends and family without losing either, the two conversations that prevent most money arguments, and the envy question. Warm, squirm-free, plain-English advice from a 66-year-old who's made every relationship-money mistake there is, and lived to tell you so you don't have to. Not advice — just what's worked.

Read more
7 min read
Getting StartedCommon SenseMoney MindsetFamily Money

The Money Equivalent of Putting On Your Own Oxygen Mask First: Why You Can't Be Generous, Invest, or Sleep from an Empty Tank

Every flight I've ever been on plays the same announcement: if the oxygen masks drop, put yours on first before helping the person next to you. It sounds selfish. It isn't. It's the most generous thing you can do — you can't help anyone from a heap on the floor because you passed out. And the exact same logic applies to your money. Yet somehow, as a culture, we've decided the opposite: that a good person puts everyone else's financial oxygen mask on first and hopes, vaguely, that there'll be something left for their own tank. So the savings account gets raided for the grown-up kids' deposit, the overtime pay goes on everyone else's needs, the emergency-fund money quietly gets spent being everyone's ATM, and the retirement pot is a distant 'I'll sort that when I've sorted everyone else.' By the time you get to yourself, the tank is empty and you're sitting on a financial aircraft that's about to experience a rapid unscheduled reinvestment. In this post I'll walk you through the hard, liberating lesson: sorting your own finances first isn't selfish, it's the precondition for being useful to anyone else. We'll cover the emergency fund as your oxygen cushion, why 'putting yourself first' is the most underrated wealth habit, how to help family without setting yourself on fire, the guilt-free version of a healthy bank account, and the simple order of operations — protect yourself, build your base, then extend outwards. Funny, warm, and genuinely useful from a 66-year-old who's learned the hard way that you can't pour from an empty cup.

Read more
7 min read
Common SenseMoney MindsetGetting StartedLessons

The 80/20 Rule of Money: The 20% That Solves 80% of Your Money Problems (and How to Actually Do It)

Vilfredo Pareto was a 19th-century Italian economist who noticed something remarkable: 20% of the pea pods in his garden produced 80% of the peas. He'd found the single most useful rule in all of personal finance, and he didn't even have a bank account worth writing home about. The Pareto Principle — 80% of results come from 20% of effort — is normally wheeled out for business books and productivity lectures. But it's the most liberating framework for your money that I've ever come across. Because here's the corollary nobody tells you: 80% of your money problems come from 20% of your money habits. Most people, when they want to improve their finances, try to fix everything. They download four budgeting apps, sign up for a money-saving challenge, cancel two subscriptions, resolve to cook every meal from scratch, and attempt to monitor every single penny. And then, on day six, they collapse, because fixing 100% of your habits is a full-time job nobody actually sustains. The Pareto approach flips that entirely. Find the 20% of your money habits that cause 80% of the pain — the one big subscription you forgot, the daily takeaway, the top-up spending that busts the budget every single time, the panic-selling that wipes years of gains — fix those few things, and suddenly 80% of your money worries evaporate without you having to budget the last £3.47 of your food shop. In this post I'll show you how to find your financial 20%, why the most expensive mistake you make is rarely the one you're worried about, and the simple, sustainable path to fixing just a handful of things.

Read more
7 min read
Spending HabitsCommon SenseBehaviourMoney Mindset

Your Money IS a Weird Zoo Animal: How to Feed It, Not Fight It (No Animal Cruelty, and It Actually Works)

Listen. I've been doing this money thing for a couple of decades now, and I've come to a profound — and frankly quite humiliating — realisation: your money is basically a weird zoo animal. It is not a rational spreadsheet. It is not a sensible accountant. It is a skittish, food-obsessed, slightly neurotic creature that responds to habits and snacks and the environment you put it in — not to willpower and lectures. Think about it. When you're skint, your money gets 'scared' and runs (or worse, hides). When there's a 'sale' sign, your money gets 'bored' and self-combusts on nonsense it doesn't even want. When you actually do the boring thing — a regular direct debit into an index fund — your money does something wild: it grows. Slowly. Relentlessly. Like a tortoise that has decided it's going to live forever. In this post I'm going to show you the five 'animals' most people have running their finances — the Salestron (hunts 3am bargains), the Subscription Snake (sheds its skin but never its £9.99 direct debit), the Future Ostrich (head in sand, pretending savings don't exist), the Panic Meerkat (sells everything whenever the market hiccups), and the Good Boy/Girl Index Tortoise (the only one actually building wealth) — and exactly how to feed each one. Funny, yes. But genuinely useful. Because understanding that your money is a zoo animal is the single biggest step you can take to stop fighting it and start feeding it properly. Warning: may cause you to recognise yourself, possibly several times, possibly with alarming accuracy.

Read more
9 min read
Investing PhilosophyCommon SenseGetting StartedMotivation

My 10 Simple Rules for Long-Term Wealth (No Spreadsheet, No PhD, No Crystal Ball Required)

After 66 years on this planet and a couple of decades of actual investing — not the theory kind, the real kind where you lose money sometimes and learn things the hard way — I've boiled what I know down to 10 rules. Not 47 rules. Not a 200-page book. Ten. Here they are, in plain English, with no jargon, no caveats so thick you need a shovel, and absolutely no 'it depends' hedging. Rule 1: Buy broad, low-cost index funds and own the world. Rule 2: Automate everything and get out of your own way. Rule 3: Ignore financial news completely — it's entertainment dressed as insight. Rule 4: Never sell in a panic (the best investors are the ones who did nothing during crashes). Rule 5: Buy less crap and invest the difference — the simplest wealth-building formula ever written. Rule 6: Check your portfolio four times a year, not four times a day. Rule 7: Keep it simple — if your strategy needs a flowchart, it's too complicated. Rule 8: Time in the market beats timing the market — every single time, over any meaningful period. Rule 9: Know your 'enough' number and stop when you hit it. Rule 10: Enjoy your life while your money works — the whole point of investing is to live well, not to die with the biggest spreadsheet. No secrets. No 'one weird trick.' Just the 10 things that actually matter, written by someone who learned most of them the expensive way.

Read more
8 min read
Investing PhilosophyCommon SenseETFsGetting Started

The Financial Industry Wants You Confused — Here's How to Beat Them at Their Own Game

Let me tell you something the financial industry would rather you didn't think about too hard: complexity is their business model. Every 1.5% actively-managed fund fee. Every structured product with a 40-page prospectus. Every 'bespoke portfolio solution' that requires three meetings and a leather folder. Every piece of jargon — 'alpha generation,' 'factor tilts,' 'tactical asset allocation' — that makes investing sound like something only people with Bloomberg terminals and Hermès ties can do. It's all designed to do one thing: make you feel like you need them. And you don't. Here's the liberating truth: a simple global ETF at 0.07-0.22% has outperformed 88-92% of professional fund managers over 15 years. That's not my opinion — that's the SPIVA scorecard. The financial services industry is a £4 trillion machine that runs on confusion, fees, and the entirely reasonable human belief that 'if it's complicated, it must be better.' It isn't. Covering: why active fund managers almost never earn their fees over the long run, how the industry invented complexity to justify its existence, the three products that are actually worth paying for (spoiler: there aren't many), why your bank 'advisor' is often just a salesperson with a nicer title, the simple two-fund portfolio that anyone can run in 15 minutes a year, and the quiet confidence that comes from realising you don't need to outsmart Wall Street — you just need to own it.

Read more
8 min read
Getting StartedCommon SenseInvesting PhilosophyLessons

The Emergency Fund That Saved My Bacon (Twice): Real Stories, Real Money & Why Cash in the Bank Makes You a Braver Investor

I know what you're thinking. 'Emergency fund? Steve, that's the most boring topic in personal finance. Even you must be struggling to make this interesting.' And you'd be right — it is boring. Until you need it. Then it's the most exciting thing in your financial life because it's the difference between 'this is stressful but manageable' and 'I am genuinely panicking.' I've had two moments in my life — proper, heart-in-mouth, 'how am I going to pay for this' moments — where an emergency fund saved my bacon. Not my ISA. Not my SIPP. Not my carefully constructed ETF portfolio. A boring, unsexy, easy-access cash account with several months of expenses sitting in it doing absolutely nothing exciting. Here are those stories, told honestly, with the actual numbers. Covering: what actually qualifies as an emergency (hint: the Boxing Day sales do not), the right amount to keep — and why the standard '3-6 months' advice might be wrong for you, where to park your emergency fund so it earns something without being locked away, why having cash in the bank paradoxically makes you a better and braver investor (because you never have to sell your ETFs in a crash to fix the boiler), how I built mine from scratch when I had precisely zero spare cash, and the psychological difference between 'I have a problem' and 'I have a problem AND no money' — which is about the size of the Grand Canyon. No spreadsheet drills. No guilt. Just two real stories from a 66-year-old who's been through it and came out the other side. The emergency fund is the least glamorous part of investing. It's also the foundation everything else is built on.

Read more
10 min read
Investing PhilosophyCommon SenseMotivationGetting StartedCompounding

Keep It Simple. Start Now. Keep Going. — The Buy Less Crap Manifesto (Or: Exactly What I Do, What This Website Is About, and Why It Actually Works)

People ask me all the time: 'Steve, what do you actually do? Like, what's the system?' And I could point them to any of the 45 blog posts or 30 buy posts on this website — but the truth is, the whole thing fits on the back of a napkin. It's so simple it almost sounds stupid when you say it out loud. But that's the point. Simple works. Simple compounds. Simple doesn't require you to be a genius or a fortune teller or someone who enjoys reading quarterly earnings reports with a cup of chamomile tea. This post is everything I believe about money, investing, and life — boiled down to its absolute essence. Covering: the three rules that run my entire financial life (and I do mean entire — there are only three), what I actually buy and why (VUAG, VWRP, and the conviction picks you see in the buy posts), the automation system that means I barely have to think about any of this, the 'Buy Less Crap' philosophy that's really about happiness disguised as frugality, why 'start now' is the most important two-word sentence in personal finance, the power of keeping going when everything feels flat (the compounding curve is a liar for the first decade and a miracle after that), what I've stopped doing that's saved me more money than any clever investment ever could, the weekly rhythm that keeps the whole thing spinning without effort, and the one thing I'd tell everyone on earth if I had 30 seconds and a megaphone. No complexity. No secret sauce. No 'advanced strategies for sophisticated investors.' Just what I do. What this website is about. And why it works — not because it's clever, but because it's simple enough to actually stick with for 20 years. This is the Buy Less Crap manifesto. This is the whole thing. Read it, steal it, make it yours. Then go do it.

Read more
8 min read
Investing PhilosophyGetting StartedMotivationCommon SenseCompounding

There Is No Wrong Age to Start (Just One Wrong Decision: Waiting Forever)

Let's get one thing straight: you are not too old to start investing. Not at 35. Not at 47. Not at 58. Not at 72. You could be 94 and I'd still tell you to open the ISA — if not for you, then for whoever you're leaving your money to. The internet is obsessed with the 25-year-old who opened a Vanguard account on their birthday and will retire at 40 on a beach made of compound interest. Good for them. But what about everyone else? What about the 52-year-old who just finished paying off the mortgage and is looking at their pension statement for the first time in a decade? What about the 41-year-old single parent who's been so busy keeping everyone alive that investing was never on the radar? What about the 63-year-old who thought they'd done enough, looked at the numbers, and quietly panicked? This post is for all of you — and for anyone who's ever muttered 'I've left it too late' while scrolling past yet another compounding chart that made them feel worse instead of better. Covering: the honest maths of starting at every age (25, 35, 45, 55, 65 — yes, 65), why 'starting later means you need to save more' is true AND completely missing the point, the years-until-you-need-the-money framework that reframes the whole conversation, how a 55-year-old with 15 years to invest still gets meaningful compounding, the psychological trap of 'it's too late now' (spoiler: that's just your brain finding an excuse not to do something mildly uncomfortable), the one thing that's worse than starting late (never starting at all), the 60-year-old's secret weapon (you probably earn more now than you did at 25), and the light-hearted truth: you're going to be 70 anyway. You can be 70 with an ISA and a SIPP, or you can be 70 without one. Either way, 70 is coming. Might as well arrive with a portfolio. No guilt. No shame. No 'you should have known better.' Just an honest, gently funny nudge from a 66-year-old who started in his 40s, made plenty of mistakes, and still ended up alright. The best time to plant a tree was 20 years ago. The second best time is now. But here's the bit people forget: the tree you plant at 55 still gives shade at 75. Plant the tree.

Read more
9 min read
Investing PhilosophyCompoundingMotivationGetting StartedCommon Sense

Start Early, Start Today, Start Now: The Happy Guide to Compounding, Buying Less Crap & Building a Life You Actually Love

If there's one thing I'd shout from every rooftop in Britain — if there were any rooftops left that weren't covered in scaffolding — it's this: start. Not next month. Not when you've done more research. Not when the market's 'calmer' or your salary's higher or the stars have aligned in some mythical perfect-investing constellation. Start today. Start now. Before you've got it all figured out. Before you feel ready. Because here's the happy truth that took me 66 years to fully internalise — the sooner you start, the less you need to save, the less you need to earn, and the more life you get to live while your money quietly compounds in the background. This post is everything I know about starting, compounding, and the genuine happiness that comes from buying less crap and investing the difference. Covering: the maths of starting early vs starting late (it's almost unfair how much easier early-starters have it), the 'coffee and a sandwich' rule that finds £100+ a month hiding in plain sight, why buying less crap isn't about deprivation — it's about making room for what actually makes you happy, the compounding curve and why the first 10 years feel like nothing and the next 20 feel like magic, how to automate your entire financial life so saving and investing happen without you lifting a finger, the psychological shift from 'I'm giving things up' to 'I'm buying my freedom', and the most important four words in personal finance: time in the market. No guilt. No shame. No 'you should have started at 18' finger-wagging. Just an honest, happy, slightly giddy reminder that the best day to start was yesterday — but the second best day is today. And today is still a very, very good day to begin.

Read more
8 min read
Investing PhilosophyCompoundingMotivationGetting StartedCommon Sense

The Sooner You Start, The Better You'll Be: Or, How I Wish I'd Started Compounding at 18 Instead of Figuring It Out at 40-Something

If someone had sat me down at 18 and explained compounding — properly explained it, with a pint and some plain English — I'd be sitting on a significantly larger pile of money right now. Not because I'd have earned more. Not because I'd have picked better stocks. Just because time would have had more time to work. This post is the chat I wish someone had had with me. Covering: the brutal (and slightly funny) maths of starting early vs starting late (spoiler: starting at 20 puts you miles ahead of starting at 40, even if the 40-year-old saves more), why 'I'll start when I earn more' is the most expensive sentence in investing, the compounding curve and why the early years look flat but the later years look like magic, how to trick yourself into starting now with whatever you've got (even if it's £25 a month), the 'coffee and a sandwich' rule that shows you how much you're actually spending on things you won't remember next week, why your biggest investing advantage isn't your salary or your knowledge — it's your remaining time on this planet, my personal list of things I wish I'd started earlier (hint: all of them), and the motivational bit: it's not too late. Whether you're 25, 45, or 65 — the second best time to start is right now. The best time was 20 years ago. The second best time is today. No guilt-tripping, no 'you should have known better' nonsense. Just honest, slightly sweary encouragement from a 66-year-old who started too late and still turned out alright. Now go open that ISA.

Read more
8 min read
Investing PhilosophyETFsCommon SenseStrategy

VWRP and VUAG: My Two Happy Places — Why These Two ETFs Are the Engine Room of Everything I Do

If you look at everything I've ever written about investing — every buy post, every strategy piece, every reflection — two funds keep showing up like a drumbeat. VWRP. VUAG. Again and again. The Vanguard FTSE All-World and the Vanguard S&P 500. They're not the fanciest ETFs in the drawer. They're not going to double in a year. Nobody's making YouTube videos about them. But they are the engine room of my SIPP, my ISA, and — honestly — my entire investing philosophy. Here's why these two boring, beautiful, dirt-cheap index funds make me genuinely happy every single day. Covering: what VUAG and VWRP actually are and why I own both instead of picking one (US tilt + global diversification = sleep-well-at-night portfolio), the 0.07% and 0.22% fees that keep almost all your money working for you, how compounding works its quiet magic in the background while you get on with living, why 'might not be optimal' is the most liberating thing I've ever said about investing, the psychological superpower of being happy with good-enough instead of chasing perfect, why comparing your returns to someone who picked the perfect stock is missing the entire point, how buying the world means you win no matter which country or sector rises next, the simple maths of regular ETF top-ups over decades (spoiler: it works, but you have to be patient), why consistency beats brilliance in long-term investing, and the honest truth from a 66-year-old who's made most of the mistakes: the best investment strategy isn't the one with the highest theoretical returns — it's the one you'll actually stick with through good times and bad. No stock tips. No market timing. No 'secret ETF the professionals don't want you to know about.' Just two index funds, regular buying, and quiet contentment. Might not be the best. Works for me. Every day getting better.

Read more
9 min read
Common SenseMindsetLife LessonsWellbeing

How to Keep Your Mind Calm, Free & Relaxed When the World Won't Cooperate: One Bloke's Guide to Not Losing Your Marbles

The world is loud. The news is designed to alarm you. Your phone buzzes 87 times a day with things that aren't urgent. Your to-do list grows faster than you can cross things off. And somewhere in the middle of all that noise, you're supposed to stay calm, make good decisions, and not lose your marbles. Good luck with that — unless you've got a system. Here's mine. Covering: why your brain wasn't designed for 24-hour news cycles and what to do about it, the 'worry window' technique that stops anxiety from leaking into your entire day, why going for a walk without your phone is the most underrated mental health tool on the planet, how to say 'no' to things without feeling guilty (and why overcommitting is a fast track to burnout), the joy of doing one thing at a time in a world that demands you do five, why comparing your behind-the-scenes to everyone else's highlight reel is making you miserable, the power of a good night's sleep and a proper laugh, how writing things down gets them out of your head so they stop circling, and the single most important lesson I've learned in 66 years: most of the things you're worrying about right now will never happen — and the ones that do, you'll handle. No meditation apps. No gratitude journals. No 'just think positive' nonsense. Just honest, practical, slightly sweary advice from a bloke who spent decades stressed about things that didn't matter and eventually figured out a better way. Your mind is the only one you've got. Might as well make it a nice place to live.

Read more
9 min read
Common SenseSpending HabitsLessonsMindset

Stop Checking Your Bank Balance (And Other Terrible Financial Advice I Actually Follow)

Some of the best money advice I've ever followed sounds completely wrong when you first hear it. Stop checking your bank balance every day. Delete the banking app from your phone. Only look at your investments four times a year. Keep a 'no-questions-asked' £50 cash stash that you can spend on anything without guilt. Delete shopping apps and make buying things slightly inconvenient on purpose. Use actual cash for certain purchases because it hurts more than tapping a card. These aren't the tips you'll find in a glossy money magazine — they're the counterintuitive, slightly odd, 'are you sure that works?' habits I've built over decades that have saved me more money and mental energy than any spreadsheet ever could. Covering: why checking your bank balance daily makes you poorer, not richer (anxiety drives worse decisions), the quarterly investing check-in system that stopped me panic-selling, why I don't have a banking app on my phone and what I do instead, the psychology of the £50 guilt-free cash stash and why it actually reduces spending, how making shopping slightly harder — deleting apps, not saving card details, waiting 24 hours — rewires your brain, the 'cash for fun, card for boring' rule that changed my discretionary spending, and the simple truth that good money habits aren't about willpower — they're about designing your environment so the easy choice is the smart one. Not advice. Just what's worked for one bloke who used to check his portfolio six times a day and was miserable.

Read more
8 min read
Common SenseGetting StartedLife LessonsHealthWellbeing

How to Stay Healthy Without Being a Bore About It: One Bloke's Guide to Eating, Moving & Not Dying Too Soon

A funny, honest, zero-preachiness guide to staying healthy from a 66-year-old who's tried every fad diet, owned three different gym memberships he never used, and eventually figured out that being healthy is mostly about not being an idiot. Covering: why the best exercise is the one you'll actually do — walking counts, gardening counts, carrying heavy shopping bags counts — the 80/20 approach to eating that means you can still have a biscuit without guilt, why your knees creak and what to do about joint health as you age, the joy of finding a sport you're terrible at, how to trick yourself into drinking more water and actually staying hydrated, the underrated health benefits of a good laugh and decent sleep (sleep hygiene for normal people, not biohackers), why comparing yourself to 25-year-olds on Instagram is a mug's game, functional fitness over 50 and bodyweight exercises for older adults, simple nutrition advice for real people who don't drink green juice, stress reduction without meditation, building healthy habits that actually stick, and the single best piece of health advice I ever received: eat food, not too much, mostly plants — with the important addendum that sometimes a bacon sandwich is good for the soul. No six-packs. No green juices that taste like pond water. Just common sense health advice, a few laughs, and the gentle reminder that your body is the only one you've got — might as well look after it.

Read more
7 min read
MotivationSavingMindsetGetting StartedCommon Sense

You Can Do This: A Motivational Guide to Saving Money, Cutting Costs & Taking Control of Your Financial Future

This is your pep talk. Not the finger-wagging, guilt-tripping, 'cancel your Netflix and never enjoy anything again' kind. The real kind. The kind that reminds you that every single day you make choices with your money — and those choices, however small they feel right now, add up to something extraordinary. Whether you're starting from zero, digging out of a hole, or just tired of feeling like your money disappears before you've done anything meaningful with it — you can do this. Covering: the 'why' that gets you out of bed and keeps you going when saving feels hard, the £5 test that changes how you see every purchase, how to find money you didn't know you had without making life miserable, the power of one good decision leading to another, how to use your emotions as fuel instead of letting them derail you, what to tell yourself when you slip up (because everyone does), and the quiet confidence that comes from knowing you're building something real. No spreadsheets. No shame. Just an honest, encouraging, slightly fired-up reminder that you are more capable than you think — and the best time to start was yesterday, but the second best time is right now.

Read more
12 min read
Getting StartedCommon SenseSavingMindsetInvesting

Save Money & Build Long-Term Goals: The Simple UK Guide to Spending Less and Creating a Future Worth Looking Forward To

Saving money isn't about deprivation — it's about creating options. This is the complete UK guide to spending less without making life miserable, setting financial goals that actually stick, and building a system where saving and investing happen automatically in the background. Covering: why most budgets fail and what to do instead, the 'pay yourself first' automation system, how to set goals that motivate rather than discourage, the difference between short-term saving and long-term investing, detailed breakdowns of the Stocks & Shares ISA and SIPP (including tax relief, allowances, platform choices, and the S&S ISA vs SIPP priority framework), Lifetime ISA, high-interest accounts, regular savers, employer pension matching, how small daily changes compound into life-changing sums, the psychology of goal-setting and why visualising your future self works, and a simple 4-step plan to go from 'I should save more' to actually doing it. No guilt, no shame, no spreadsheet marathons. Just a practical, sustainable system for anyone who wants to spend less, save more, and build a future worth getting excited about — without giving up everything they enjoy today.

Read more
9 min read
Spending HabitsCommon SenseGetting Started

Stop Paying the Loyalty Tax: How Staying Loyal to the Same Insurers, Broadband & Utilities Costs UK Households £1,000+ a Year

Loyalty doesn't pay — it costs you. UK insurers, broadband providers, energy companies, and mobile networks all operate on a 'loyalty penalty' model: competitive rates for new customers, steady price increases for everyone who stays. The FCA estimates that loyal customers overpay by £3.4 billion across insurance markets alone. Add broadband, mobile, energy, and banking, and the typical household loyalty tax is easily over £1,000 a year. Here's the full breakdown — what it costs, where it hides, and the 4-hour annual system that stops the loyalty tax dead in its tracks. Including exact comparison sites, calendar reminders, and the 'automatic no' email template that saves you the hassle of haggling.

Read more
8 min read
Spending HabitsGetting StartedCommon Sense

The Supermarket Switcheroo: How I Cut My Grocery Bill 35% Without Buying Anything Different

Same pasta. Same loo roll. Same washing-up liquid. Same basket, different supermarket — 35% less. The UK grocery market is one of the most competitive in the world, and the pricing differences between Tesco, Sainsbury's, Asda, Morrisons, Aldi, and Lidl on identical or near-identical products are far larger than most people realise. Own-brand products — from M&S to Aldi — are often made in the same factories by the same manufacturers. The yellow-sticker reductions follow predictable daily and weekly patterns. And where you shop in the store (eye-level = premium, bottom shelf = value) is a pricing decision made by the supermarket, not a quality signal. Here's everything I've learned about supermarket psychology, the exact swaps that save the most money with zero quality difference, and a shopping routine that trimmed £73 a month from my grocery bill without changing a single thing I eat.

Read more
9 min read
Getting StartedCommon SenseMoney Hacks

Free Money You're Leaving on the Table: Bank Switching Bonuses, Cashback, Pension Matching & Other UK Freebies Worth £1,500+

There is genuinely free money available to almost every UK adult, and most people leave it sitting there unclaimed year after year. Bank switching bonuses (£150-£200 per switch, do it once or twice a year), cashback credit cards and apps that pay you for money you were going to spend anyway, workplace pension employer matching (leaving free money from your employer on the table if you're below the match threshold), Lifetime ISA government bonuses (25% free top-up from HMRC up to £1,000/year), tax-free childcare and marriage allowance that eligible couples never claim, premium bond prizes, and the Help to Save scheme for lower-income earners (50% bonus from the government). Individually they're small. Together — with zero risk, zero investment, and zero lifestyle change — they can easily add up to £1,500+ in the first year. Here's the complete list, eligibility criteria, step-by-step instructions, and exactly which ones I've used myself.

Read more
9 min read
MindsetLife LessonsGetting Started

The Compound Effect in Real Life (Not Just Money): How Tiny Daily Actions Became a Life I Actually Want to Live

Everyone talks about compound interest on your money. Nobody talks about compound interest on your mornings, your habits, your health, or your peace of mind. But here's the thing — the same maths that turns £5 a day into a small fortune over 30 years also turns a 10-minute morning walk into a body you feel good in, one honest conversation a week into a marriage that actually works, and one 'no' to something you don't want into a life you chose, not one that just happened to you. The compound effect is the most powerful force in the universe — and investing is just the smallest, easiest application of it. Here's where it gets really interesting.

Read more
8 min read
Spending HabitsCommon SenseLessons

The £10 Rule: How I Caught £4,200 a Year in Spending I Didn't Know I Was Doing

Not the big purchases — the stupid, small, recurring ones you've forgotten about. The £10 Rule is a simple mental framework for catching the invisible spending that leaks from your bank account every month: auto-renewals you never use, 'just this once' purchases that became weekly, tiny subscriptions that add up to mortgage payments. I tracked every sub-£10 transaction for a month and found over £350 in things I genuinely didn't know I was paying for. Here's how the £10 Rule works, the psychology behind why small spending is invisible, and the 15-minute system that plugs the leaks without making your life feel restricted.

Read more
9 min read
Spending HabitsGetting StartedCommon Sense

The One-Hour Money Audit: Find £500+ In Savings Before Your Next Cuppa Goes Cold

One hour. That's all it takes. Sit down with your bank statements, a notebook, and a strong cup of tea — and go hunting for the money you're haemorrhaging without realising it. I've done this every year since 2018 and I've never once found less than £500 in annual savings. Subscriptions, banking fees, overpriced insurance, unused memberships, premium account charges, forgotten direct debits — the list is always longer than you expect. Here's the exact step-by-step audit process, the questions to ask about every recurring payment, the 'Cancel First, Reactivate If You Miss It' rule, and the spreadsheet template I use to turn one hour of honest scrutiny into hundreds of pounds back in my pocket every single year.

Read more
8 min read
Spending HabitsMindsetLessons

Buying Things Doesn't Fix Feelings: Breaking the Retail Therapy Cycle for Good

Bad day → open browser → add to basket → brief dopamine hit → guilt → repeat. Retail therapy is a £4.5 billion-a-year industry in the UK alone, and it doesn't work. The high lasts about as long as the checkout confirmation email, and then you're left with less money and the same feeling that sent you shopping in the first place. Here's the neuroscience of emotional spending — why your brain confuses buying things with solving problems — and the simple, practical alternatives that actually make you feel better without costing a penny. Including the 'Feelings Before Purchases' journal method that changed everything for me.

Read more
7 min read
MindsetFinancial IndependenceLife Lessons

The Richest Person in the Graveyard: Why Your Enough Number Matters More Than Your Net Worth

There's a version of you that dies with millions in the bank and a lifetime of 'one day' never lived. Nobody lies on their deathbed wishing they'd bought more VUAG. Your enough number — the point at which more money stops buying more happiness — is the most important financial calculation you'll ever make. Here's how to find yours, why it's probably lower than you think, and the liberating maths of knowing when you've already won.

Read more
8 min read
MindsetMistakesLife Lessons

Comparison Is the Thief of Wealth: Why Looking at Everyone Else's Portfolio Is Making You Poorer (And Miserable)

Someone on Reddit made 400% on a meme coin. Your neighbour drives a car you can't afford. Your brother-in-law 'got in early' on Nvidia. And you're sitting there with your boring index funds feeling like a chump. Stop. Comparison is not just the thief of joy — it's the thief of actual returns. The data shows that investors who compare themselves to others make worse decisions, chase performance, take excessive risk, and end up with less. Here's the liberating truth: the only portfolio that matters is yours, and the only benchmark is whether you're on track for your life — not someone else's highlight reel.

Read more
9 min read
Getting StartedInvesting PhilosophyCommon Sense

Pound-Cost Averaging vs Lump Sum Investing: What the Data Actually Says (UK Guide)

When you have a lump sum to invest, should you dump it all in at once or trickle it in over time? The research is clear — Vanguard found lump sum beats pound-cost averaging about two-thirds of the time. But the real answer isn't just about the maths. Here's the honest breakdown: what the data says, when DCA makes sense despite the numbers, the behavioural case for drip-feeding, and what I actually do with my own money when a lump sum lands in my account.

Read more
10 min read
Investing PhilosophyMistakesLessons

The Psychology of Market Timing: Why Smart People Keep Trying to Outsmart the Market (And Losing)

Every investor knows you can't time the market. And yet almost every investor tries — buying after rallies, selling after crashes, waiting for the 'right moment' that never arrives. Here's the neuroscience: why dopamine, loss aversion, and recency bias conspire to make market timing feel like wisdom when it's actually destruction. The Dalbar study shows the average investor underperforms the S&P 500 by 4-5% a year — not from bad funds, but from bad timing. Here's what that costs over a lifetime, and the simple system that removes the temptation entirely.

Read more
9 min read
Investing PhilosophyGetting StartedETFsCommon Sense

The Market Is At An All-Time High — Should I Invest Now or Wait For A Crash?

If you'd invested only at S&P 500 all-time highs over the last 50 years — literally picking the worst possible days — you'd still have done remarkably well. The market is at record levels more often than people realise, and waiting for a crash has historically been the most expensive strategy available. Here's the data, the 'Bob the world's worst market timer' story that everyone should read once, and why I keep buying VUAG every single week regardless of what the index is doing.

Read more
12 min read
ETFsInvesting PhilosophyGetting StartedCommon Sense

Why VUAG Is My Main Holding — The S&P 500 ETF I Buy Every Week, the Power of Compounding, and Why I Always Reinvest Everything

The Vanguard S&P 500 UCITS ETF (VUAG) is my largest holding and my go-to investment inside my SIPP. I try to buy as much of it as I possibly can — every week, rain or shine, without fail. Here's the full case: why VUAG over other ETFs, the maths of compounding that most people underestimate, why I always reinvest every penny of income, and how a simple S&P 500 tracker at 0.07% became the engine of my entire pension strategy.

Read more
10 min read
Getting StartedInvesting PhilosophyCommon Sense

How to Protect Your Money From Inflation (What I Actually Do, Not Theory)

Inflation is a silent wealth destroyer — at 3% it halves your purchasing power in 24 years, at 5% in 14. Yet most UK savers leave money in accounts paying less than inflation, quietly getting poorer every year. Here's exactly what I do to protect my money: the investments that historically outpaced inflation, the cash trap most people fall into, why premium bonds and easy-access savers are costing you money, the ETF allocation I trust, and the simple rule that keeps me from panicking when prices rise. No jargon, no crystal ball — just what's actually worked.

Read more
10 min read
Investing PhilosophyGetting StartedLessons

How to Prepare for a Recession (The Plain-English Guide I Wish I'd Had in 2008)

I lived through 2008 and made every mistake in the book — panicked, sold at the bottom, stayed in cash too long, and missed the recovery. Recessions are normal: the UK has had one roughly every 9 years since 1945. Here's what I do differently now: the emergency fund that means I never have to sell in a downturn, the portfolio allocation that lets me sleep, the psychological preparation that stops me making the same mistake twice, and why a recession is actually good news for anyone still buying. No fear-mongering, no predictions — just the practical prep that turns a recession from a crisis into an opportunity.

Read more
9 min read
Investing PhilosophyCommon SenseGetting Started

You Don't Need to Retire at 40 — Barista FI and the Case for Financial Independence Lite

The FIRE movement accidentally convinced a generation that financial independence means quitting work forever and living on £18,000 a year. It doesn't. Barista FI is the saner middle ground: save enough that your investments cover your basics, then work part-time, freelance, or do something you actually enjoy while your portfolio grows the rest of the way on its own. Here's the maths with real UK numbers, how much you need, the Coast FI crossover, and why the goal isn't stopping work — it's having enough that work becomes optional.

Read more
10 min read
ETFsInvesting PhilosophyGetting StartedCommon Sense

How to Build a Two-Fund Portfolio in the UK (The Simplest Investing Strategy That Actually Works)

If there's one thing I've learned after decades of investing, it's that complexity is expensive and almost never necessary. One global equity ETF plus one bond ETF — that's the entire portfolio. Here's the exact two-fund setup for UK investors: which ETFs, the allocation by age, the step-by-step platform setup, and why simplicity has outperformed most professional fund managers over the long run. No jargon, no unnecessary tilts — just what actually works.

Read more
9 min read
Investing PhilosophyMistakesCommon Sense

Why I Stopped Watching CNBC (And My Portfolio Thanked Me)

For fifteen years I started every morning with financial news. Then I realised the business model of CNBC, Bloomberg, and market commentary isn't to make you a better investor — it's to keep you watching. Here's the research on why consuming financial news makes you trade more and earn less, the Fidelity dead-people study, and the simple quarterly check-in system that replaced my morning market obsession.

Read more
10 min read
ETFsInvesting PhilosophyCommon Sense

FTSE All-World vs S&P 500: Which ETF Actually Belongs in Your ISA? (Plain English UK Guide)

The question I get asked more than any other: should I buy a global tracker or go all-in on America? Here's the honest comparison — performance, concentration risk, currency exposure, fees, and what I actually hold in my own ISA. The global tracker is the sensible, boring, diversified answer. The S&P 500 position is the conviction tilt. For someone just starting out, the real answer is simpler than most people think.

Read more
9 min read
Getting StartedCommon SenseInvesting Philosophy

How Much Should I Be Investing Each Month? (The Honest Answer, No Hustle-Bro Nonsense)

The 50/30/20 rule says save 20%. But for most UK households — especially renters in cities — that number is completely unrealistic. Here's the sustainable surplus method: find your actual take-home pay, subtract your real essentials, keep a reasonable discretionary budget, and invest the gap. With worked examples from real UK salaries, from £28k in Manchester to a family of four in Bristol. Plus the investing waterfall: employer match first, then ISA, then SIPP. No guilt, no arbitrary percentages — just a number you can genuinely stick to.

Read more
9 min read
Investing PhilosophyLessonsMistakes

Stop Checking Your Portfolio (Why Looking Less Makes You More Money)

Markets go down on 47% of all trading days. Check daily and you'll see a loss almost half the time — and your loss-averse brain will make terrible decisions as a result. The Nobel Prize-winning concept of myopic loss aversion explains why Fidelity's best-performing accounts belonged to dead people, why the average investor earns 3-4% less than the funds they own, and why the single best thing you can do for your returns is delete the investing app from your phone. Here's the research, the neuroscience, and the practical system I use to check only four times a year.

Read more
9 min read
Getting StartedCommon SenseInvesting Philosophy

Why Cash ISAs Are a Trap (And What I Moved My Money Into Instead)

From April 2027, the government is capping cash ISAs at £12,000 for under-65s. But here's the thing — cash ISAs have been quietly costing you money for years. Inflation erodes your 'safe' savings while stocks and shares ISAs compound real growth. Here's exactly what I moved my cash into, why I stopped treating cash as 'safe' and started treating it as 'guaranteed to lose purchasing power', and the simple ETF allocation I use instead.

Read more
8 min read
Spending HabitsInvesting PhilosophyCommon Sense

The Latte Factor Is a Lie (And What Actually Builds Wealth)

For twenty years, personal finance gurus have been telling us that cutting out small daily luxuries — the famous 'latte factor' — is the key to building wealth. It makes for a good headline but it misses the point entirely. Shaming people for buying coffee while ignoring stagnant wages, housing costs, and systemic barriers is lazy advice dressed up as wisdom. Here's what actually moves the needle: earning more, investing the gap, and automating the whole thing so you don't have to think about every cappuccino. The real latte factor isn't the coffee — it's the decade you spent not investing while worrying about the coffee.

Read more
8 min read
Common SenseLessonsInvesting Philosophy

How to Talk to Your Partner About Money Without It Turning Into an Argument

Money is the second most common cause of arguments in British relationships — behind only housework. Yet most couples spend more time planning their summer holiday than talking about their financial future. After 40 years of marriage, here's what I've learned about having honest money conversations: the 'money date' that works when nothing else does, why 'we need to talk about money' is the worst opener, the power of shared goals over shared spreadsheets, and the one question that changed how we think about spending forever. No guilt, no blame, no his-and-hers budgets — just two people rowing in the same direction.

Read more
9 min read
Getting StartedETFsCommon Sense

Dividend Investing for UK Investors: What I Actually Do (Plain English, No Jargon)

Dividends are one of the most misunderstood parts of investing. Some people treat them like free money. Others ignore them completely. Here's the plain-English truth about dividend investing in the UK — the tax rules, the ETFs I hold, the dividend allowance trap most people miss, accumulation vs income funds explained, and why my approach is 'own the market and take the dividends as they come' rather than chasing yield.

Read more
8 min read
Getting StartedInvesting PhilosophyCommon Sense

Starting Investing Late In Life Is Better Than Never Starting At All (The Over-50 Guide)

The internet is full of advice for 25-year-olds starting their investing journey. What about everyone else? If you're over 50 and just getting started — or feel like you've left it too late — this is for you. Here's the honest maths of starting later, why it's still absolutely worth doing, the accounts to prioritise, the allocation that makes sense with a shorter runway, and the psychological shift from 'I've missed the boat' to 'I'm getting on board today.'

Read more
8 min read
Getting StartedCommon SenseLessons

How to Read Your UK Pension Statement (And Actually Understand What It Means)

27% of Brits can't name their own pension provider. Even more have a pension statement sitting unread because it might as well be written in Latin. Here's the plain-English guide to reading your pension statement — every section explained, the numbers that actually matter, how to spot high fees leaching your returns, and the one-page pension check-up that takes 15 minutes and could add thousands to your retirement.

Read more
8 min read
Getting StartedETFsInvesting Philosophy

Trading 212 Pies: The Simple Investing Tool I Wish I'd Discovered 30 Years Ago

Trading 212's Pie feature lets you auto-invest across multiple ETFs and shares with a single click, at your chosen percentages, pound-cost averaging into your targets every time. Here's exactly how Pies work, why they're the best behavioural investing tool I've found, my current Pie setups inside my SIPP and ISA, and the psychology behind why auto-allocation beats manual decision-making every time.

Read more
9 min read
Getting StartedCommon SenseInvesting Philosophy

SIPP vs ISA: Which Tax Wrapper Should Your Money Live In? (The Honest UK Guide)

The UK gives you two of the best tax-advantaged investing accounts in the world: the Stocks & Shares ISA and the Self-Invested Personal Pension (SIPP). Most people don't understand the difference — or why it matters enormously over decades. Here's how I split my money between the two, the tax maths that most articles skip, when you should prioritise one over the other, and the simple framework for deciding where your next pound should go.

Read more
8 min read
Investing PhilosophyLessonsMistakes

The Power of Doing Nothing: Why The Best Investors Are The Laziest Ones

The biggest mistake I made in 40 years of investing wasn't buying the wrong stock — it was doing too much. Fidelity found their best-performing accounts belonged to dead people. The SPIVA scorecard shows 88-92% of active fund managers lose to a simple index fund. Here's the overwhelming evidence that doing nothing beats doing something, why inactivity is a competitive advantage in investing, the psychology behind our addiction to tinkering, and the simple systems I now use to protect my portfolio from myself.

Read more
9 min read
Getting StartedLessonsInvesting Philosophy

The Money Lessons My Parents Never Taught Me (And What I'm Teaching My Own Kids Instead)

Most British parents never talked to their kids about money — not because they didn't care, but because they were never taught themselves. Here's the generational silence around personal finance, what it cost me, the financial education gap in UK schools, and the 7 money lessons I'm teaching the next generation that compound far beyond compound interest.

Read more
9 min read
Investing PhilosophyMistakesLessons

What Actually Happens When The Stock Market Crashes (And Why I Don't Sell)

Markets crash. It's not a matter of if, but when — every 6-7 years on average the FTSE or S&P 500 drops 20% or more. Yet panic-selling is the single biggest destroyer of long-term returns. Here's exactly what happened in 1987, 2000, 2008, 2020, and 2022 — the crashes, the recoveries, the human cost, and why history teaches one lesson above all: the investors who do nothing during a crash almost always win.

Read more
8 min read
Investing PhilosophyCommon SenseGetting Started

What's Your 'Enough' Number? (The Question That Changed How I Think About Money Forever)

Most people spend decades chasing more — more income, more growth, more returns — without ever defining what 'enough' would actually look like. Here's the framework for finding your enough number, why it's the most important financial calculation you'll ever do, and how it transforms your relationship with money from fear and scarcity to gratitude and choice. Includes the 4% rule, Coast FI, and the psychology of knowing when you've won the game.

Read more
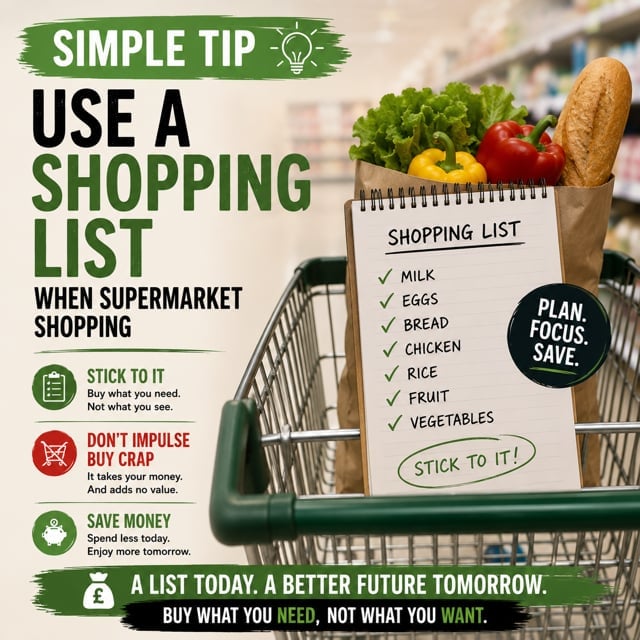
Shopping smarter infographic — make a list, stick to it, don't impulse buy crap, save money today to enjoy more tomorrow, buy what you need not what you want.

Don't miss a post

Get honest reflections on ETFs, compounding, mistakes, and what I do with my own money — straight to your inbox. No spam, no hype, no nonsense.

Your email is never shared. Unsubscribe anytime. Nothing on this site is financial advice.

For educational purposes only. This content provides general information about spending habits, saving and personal finance. It is not financial advice or a recommendation to take any financial action. Always consider your own circumstances before making financial decisions.

Read full disclaimer